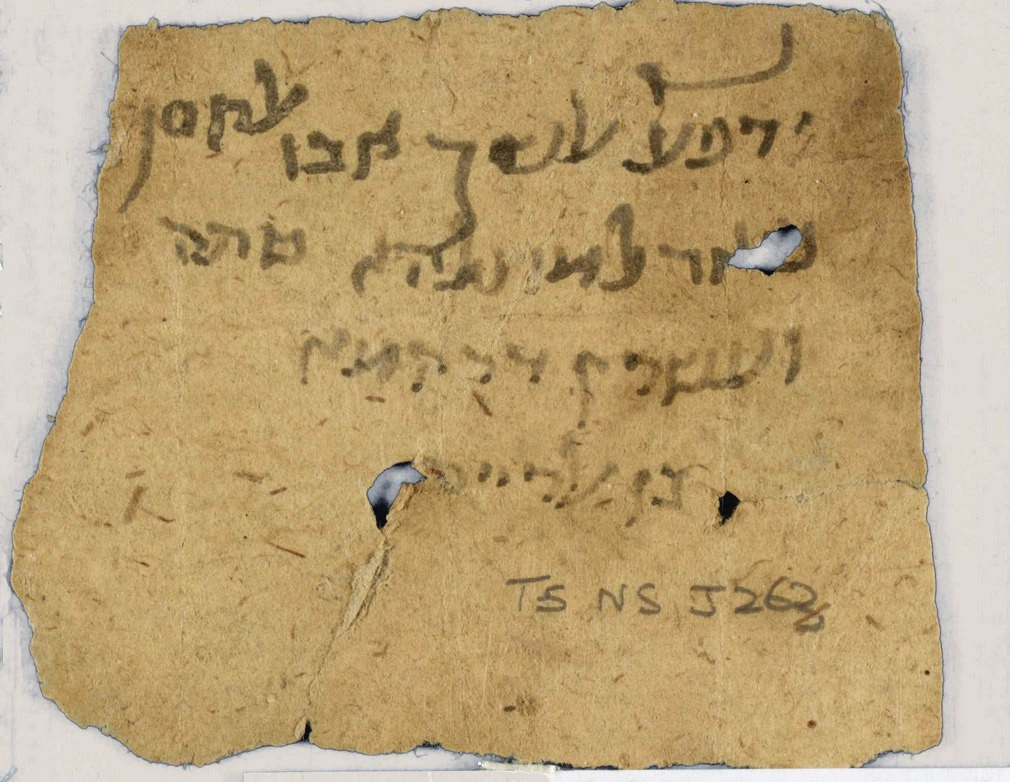
A suftaja from ca. 12th century Egypt, written on paper. Taylor-Schechter Genizah Collection; University of Cambridge.
The Prohibition of Loaning at Interest
The Covenant Collection, Exodus 20:19–23:19, presents a host of laws that address the needs of pastoral, agricultural, and urban societies, ranging from regulations concerning loose livestock on another’s grazing land (Exod 22:4) to those concerning proper treatment of the poor and disenfranchised (Exod 22:20–26).
The prohibition to take interest payments on loans is found between the prohibition to mistreat widows and orphans, and the requirement to return a poor man’s pledged garment at night:
שמות כב:כד אִם כֶּסֶף תַּלְוֶה אֶת עַמִּי אֶת הֶעָנִי עִמָּךְ לֹא תִהְיֶה לוֹ כְּנֹשֶׁה לֹא תְשִׂימוּן עָלָיו נֶשֶׁךְ.
Exod 22:24 If you lend silver to My people, to the poor among you, do not act toward them as a creditor; exact no interest from them.
This verse emphasizes the poverty of the borrower. In his commentary on Exodus, William Propp notes:
It is important not to impose our capitalist assumptions on ancient Israel. [Alan] McNeile… contrasts the modern loan, often a business investment, with the biblical loan to alleviate poverty. [Cornelis] Houtman… gives the example of someone who has exhausted his/her food supplies and needs charity to tide them over until the next harvest. The needy one would be entitled to borrow from a more fortunate neighbor without paying interest for “such aid is thought of as a charitable deed…”[1]
A short-term loan granted without interest allows a farmer to maintain his field, or a shepherd his flock, keeping the household afloat during a hard year. The hope would be that during the next year, the loan could be paid back. While the verse in Exodus speaks only about silver,[2] the Deuteronomic Law Collection[3] and the Holiness Collection in Leviticus[4] forbid interest taking on loans of goods as well.
Adapting to a Commercial Economy
The Torah’s prohibition makes sense as an ethical norm when speaking about an economy based on subsistence farming, in which people can grow what they need to subsist, and barter their produce for other goods. In such an economy, loans are small, short-term, and made on an emergency basis.
As populations grew, cities formed, and markets developed, the demand for liquid capital in ancient economies expanded, and the restraints imposed on loans became onerous in a commercial economy.[5] The Torah does not address this type of market economy, as Carol Meyers writes in her commentary on Exodus:
No cases or exhortations deal with a commercial credit system, for Israel’s economy was not one in which resources were lent for entrepreneurial ventures.[6]
But times changed, and many later Jews lived in a market economy. Wishing to honor the Torah’s laws while at the same time not crippling their abilities to participate successfully in a commercial economy, they were left in a bind.
The prohibition of loans with interest would have been very difficult for large-scale farmers, who produce to sell or trade much of what they grow. Such a business requires heavy early investment in equipment, manpower, and purchase of seed;[7]startup money is called “seed capital” for a reason.[8] Jews wishing to pursue a life as traders, merchants, or even urban craftsmen would have had a difficult time without the capital to start or maintain their businesses.
In theory, rabbinic law could have made a distinction between charitable loans and business loans, thus avoiding the problem altogether, but they did not go that route.[9] Instead, rabbinic law came up with a number of loopholes, based on the idea that it was only forbidden to charge individuals interest and not institutions. The most famous of such loopholes are the prozbul document, which transfers debt to the court and allows the person to collect on the court’s behalf, and the heter isqa document, which turns a loan into a business partnership. These documents covered long-term investments, but this still left many more minor transactions riddled with interest problems.
The Problem of Price Adjustments
For example, let us say that a local seller wishes to lock in the price of a certain amount of produce—for instance, making a deal to pay a farmer for twenty bushels of wheat before they ripened. The rabbis forbade this practice (m. Bava Metzia 5:7):
אין פוסקין על הפֵּרות עד שיצא השער
One may not set a price regarding the purchase of produce until the market price is set.
The rabbis’ thought that setting a price in advance, and paying upfront, could look as though the purchaser is lending money at interest: If the market price goes up, when the farmer delivers the twenty bushels (now worth more than the agreed-upon price), it would look as though the farmer is paying interest to the lender for advancing him the money.
The rabbis realized that even this relatively minor limitation on a common business arrangement stymied commerce and hamstrung markets, and so they restricted this rule to cases in which the price is set by clear outside forces (think of the Kelley Blue Book for cars). Thus, the Tosefta states (t. Baba Metzia 6:5):
אין פוסקין לא על האפרוחין ולא על הפרגיות ולא על הדגים שבטבריא ולא על חבילי קש אבל פוסקין על הביצים ועל הצפרים ועל הדגים שבשאר כל מקומות ועל חבילי עצים
One may not set an advanced price for chicks, young chickens, fish in Tiberias, or bushels of straw, but one may set an advanced price on eggs, birds, fish anywhere else (other than Tiberias), and for bundles of wood.
זה הכלל כל שיש לו גורן קוצץ עמו כשער גורן וכל שאין לו גורן פוסק עמו כשעה שירצה.
This is the principle: Anything that has a season, the price must be established according to the market pricing of that season. Anything that does not have a season, the price can be established whenever the parties want.
The permission for buyers and sellers to agree to prices in advance, other than where prices were fixed by the market, gave merchants and buyers flexibility.
Tacit Interest: The Introduction of Credit
Rav Nahman, a second generation Babylonian Amora living in Nehardea, took this a step further and permitted something called טרשא (tarsha), tacit interest (b. Bava Metzia 65a). In this practice, the seller would allow the buyer to delay payment, and the buyer would offer a higher price than usual for an item. Of course, what is actually happening here is that the buyer is paying extra for the convenience of being able to pay later, i.e., he is taking a loan on credit and paying it back with interest.
Nevertheless, the commentators explain that since we are speaking of products without a fixed market price,[10] as long as seller does not say explicitly that the cost would be less if the buyer were to pay immediately, we may act as if this is not an interest payment, but just a higher price for the item.
Permitting tacit interest provided some liquidity at the local level—that is, when buyer and seller were in the same place, but something more robust was necessary for travelling merchants.
Long-Distance Trade
In late antiquity, urbanization gave rise to long distance trade, and Jewish involvement in this trade could be hamstrung by a lack of access to liquid capital. Hillel Gamoran, a historian of rabbinic economics, explains that even Tannaim were aware of a need for credit in long distance trade,[11] and that they carved out an exception to usury law for agents transporting merchandise on behalf of their principals (t. Baba Metzia 4:8):
...חמרין מקבלין מבעל הבית ומעמידין למקום היוקר כשער הזול ואין חוששין
…Donkey drivers can purchase goods [in a place where they are cheap] and then sell them in a place where they are expensive at a lower price and need not worry.
The point, Gamoran argues, is that the travelling merchant can set a lower price with a person living in an area where the goods are expensive. He can then travel to a place where the goods are cheap, purchase them for an even lower price, and then bring them to the original purchaser. The benefit here is that the purchaser gets a lower price than available in his region, but since the merchant is paying an even lower price when he buys the goods elsewhere, he too will gain. Granting the merchant credit for his labor, the rabbis decided to consider this as a wage for his work and not as a loan paid back with interest.
The Suftaja: A Solution in the Islamic Period
In the Geonic period (roughly 600–1100 C.E.), long-distance trade was further facilitated by Islamic conquest of the southern Mediterranean. This expansion of trading networks and the demands of the marketplace in the high middle ages led to further developments in Jewish law, including the gradual acceptance of a long-distance bill of payment, known as a suftaja.
The term literally means “order of payment” but most dictionaries translate it as “bill of exchange.” This instrument, known from Arabic papyri as early as the ninth century, allowed merchants and their partners to sidestep the dangers of carrying money and provided them with liquid funds on which they could draw on far away from home.
The suftaja may be seen as akin to modern travelers’ checks or bank checks—traders could go from one place to another and use the suftaja as a letter of credit without worrying about losing their money to a shipwreck or robbers attacking a caravan.
Here, for example, is a typical suftaja (see image above):
بسم
ידפע אלשיך אבו אלחסן
כיאר למוצלהא סתה
ועשרין דרהמא
בן אלרייס
In the name [of God]
The Elder, Abū al-Ḥasan Khiyār,[12] shall pay
its bearer six
and twenty dirhams
[I]bn al-Rayyis[13]
The text is written in Judeo-Arabic, with Hebrew characters, except for the opening phrase which is in Arabic characters, but written in shorthand. There are three parties to the transaction mentioned in the document: the unnamed bearer, the borrower or local banker (Ibn al-Rayyis) with whom the deposit would have been made, and the distant banker (Abū al-Ḥasan Khiyār) from whom bearer would come to collect his 26 dirhams in cash. All parties here are Jews.
Convenience as a Benefit
The halakhic problem with the suftaja is that it gives the depositor a benefit—convenience and security in moving money over long distances. Since the depositor has placed money in the hands of another person, the suftaja could look like a loan bearing a form of tacit interest—that is, that the depositor loans the money, and in return, will get his money back plus the benefit of the security the suftaja brings him.
Security may not be a tangible benefit, but it definitely has cash value, which is why modern banks charge for the service. It is not quite the same as when modern banks gave out toasters in return for opening an account,[14] but for the rabbis, it still smacked of tacit interest. In today's economy, dominated by debit and credit cards, we take this convenience for granted, but imagine having to worry about carrying around the entire contents of your savings account wherever you go.
The suftaja was a financial leap forward, and in a world where this option existed for Muslim businesspeople, Jewish ones would need to make use of it too or lose any ability to compete in the market.
Halakhic Compromise
The geonim addressed the problem in their halakhic works and responsa, figuring out ways to permit the use of the suftaja. For example, Samuel b. Hophni Gaʾon, head of the talmudic academy in Sura (in Babylonia) from 998 till his death in 1013, wrote a monograph on the suftaja called Kitāb al-Ḥawāla wa-l-Asfatāʾij (The Book of IOUs and Letters of Credit). This work, likely drawing on Islamic law, is no longer extant, but ostensibly provided Jewish merchants with guidelines for how to do business within the confines of Jewish law.
Other authorities were more circumspect, and only allowed it on grounds of necessity. Thus, Hai Gaʾon,[15] Samuel b. Hophni’s son-in-law, wrote a responsum[16] on the matter when asked about a dispute in a suftaja case:
ושאלת על הספאתג. ואיך ידונו [בית דין] אם כתב ראובן לשמעון ספתגה ממדינה למדינה ושמעון מסרו ללוי שקבלו ממנו ואחר כך הכחיש. ומי שמסר והוא [המקבל השני] מודה שלא נתן. אם יכול שמעון לחזור על ראובן ולתבוע ממון הספתגה לפי שלא קבל מלוי כלום או לאו?
You asked about the suftaja, how [a court] would judge if Reuben wrote Shimon a suftaja from one country to another, and Shimon gave it to Levi, who took it but refused to pay anything, and both parties admit that [Levi] did not pay any money, can Shimon return to Reuben and demand the money he deposited for the suftaja back, since he never received any cash from Levi, or can he not?
Rav Hai first responds by saying that the very institution of suftaja goes against Jewish law.
כך ראינו שאין בשרשי הדינים שלנו [להתיר] לשלוח הספתגה לפי שאמרו רבותינו אין משלחין מעות בדיוקני ואפילו עדים חתומין עליה.
This is what we see: In our legal sources, we cannot permit the use of a suftaja since our rabbis said (b. Bava Kama 104b): “One may not send money [as credit] based on a sign, even if witnesses sign to it.”
According to the way Rav Hai reads this source, credit is prima facie illegitimate halakhically. Nevertheless, Rav Hai does not stop here:
אבל בשביל שראינו שהבריות משתמשין כה התחלנו לדון על פיה כדי שלא יתבטלו המסחרים בין האנשים. וקבלנו לדון בה כמשפט התגרים לא להוסיף ולא לגרוע. וכך הוא הדין ואין לשנות ממנו דבר.
Nevertheless, because we see that people use this document, we have begun to make judgments based upon it, so that trade not be banished from among the men. We have decided to follow the rules like the merchants do, not to add or subtract to them. This is the law, and one should not change anything about it.
Thus, Rav Hai grudgingly opens the door to the suftaja’s acceptance since “non-recognition of the document would have been liable to harm the regular course of trade.”[17] He buttresses this with the rhetorical flourish, evoking the prohibition of adding or subtracting to the Torah (Deut 13:1) for a practice that changes Torah law!
Adapting to New Economic Realities
As we have seen above, despite the rabbis’ belief that any extra benefit accrued to a lender was a violation of the Torah’s prohibition against usury, rabbinic authorities found a way to accommodate the needs of the mercantile marketplace.[18] In the rabbinic period this meant finding loopholes for price-fixing and in the geonic period it extended to allowing credit instruments such as the suftaja to be used by Jewish merchants. These halakhot highlight the perpetual engagement of Jewish legal authorities to bridge the gap between the economic realities imagined by the Torah and their own world.
